Connected-car services are turning trip, driving and vehicle-health data into a potential input for motor-insurance, lending and fleet decisions, according to a 04 Oct 2026 report by The Economic Times. For Indian drivers, the immediate point is not a confirmed premium change: it is to understand what a connected car or app records, why it is used, who receives it and what happens if consent is withdrawn.
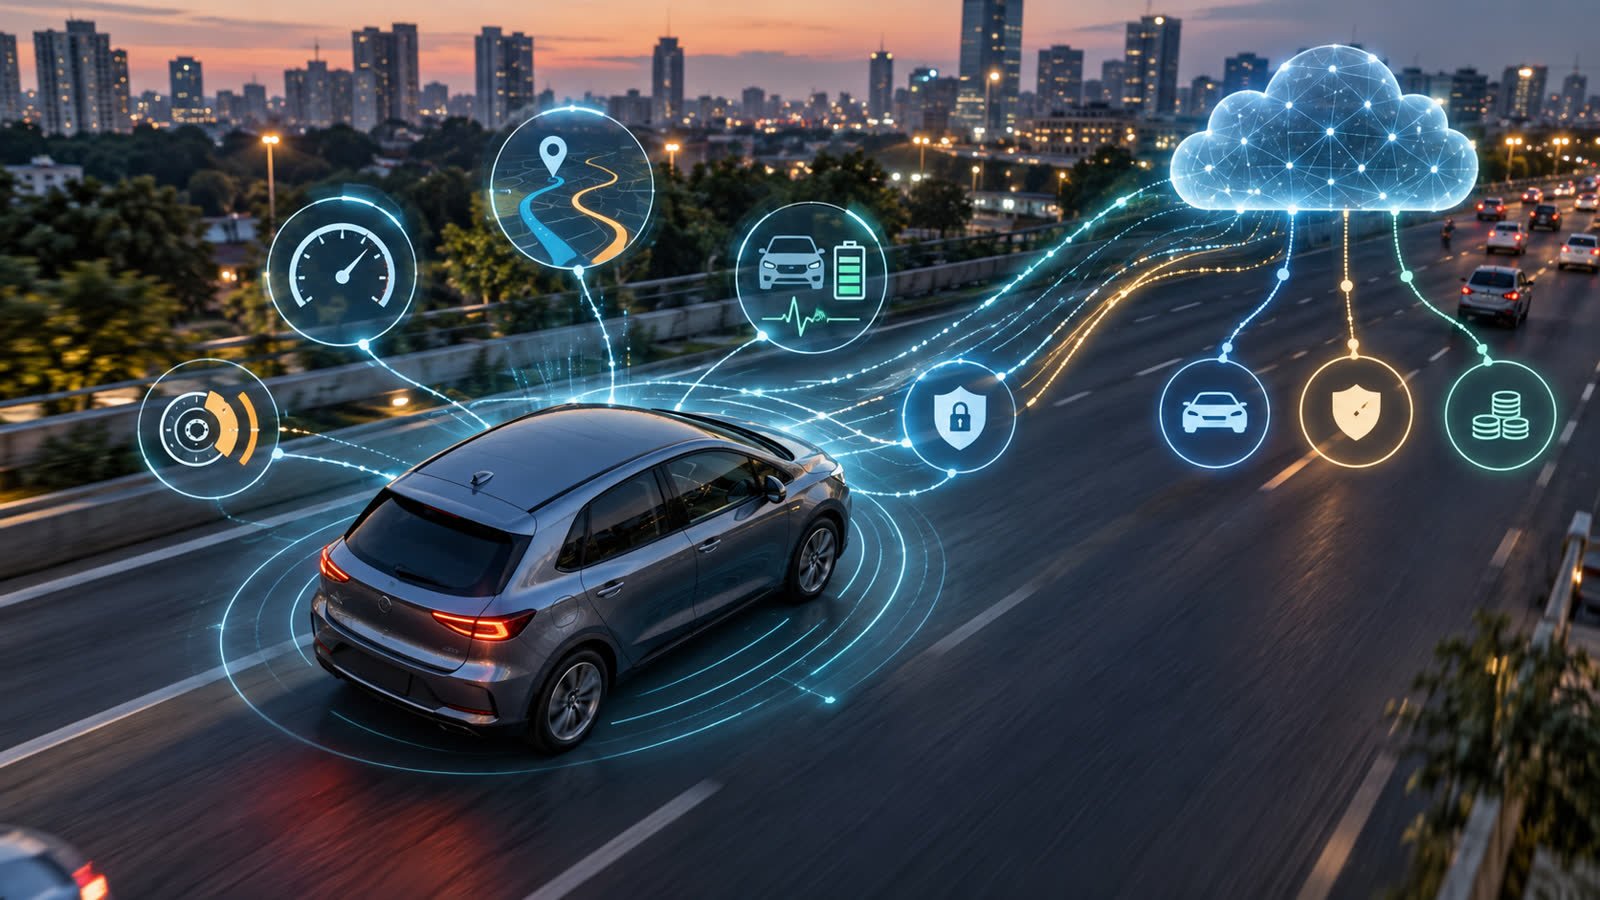
 Illustrative graphic: connected-car data flows shown conceptually; not a photo of a specific vehicle, insurer or lender. Credit: FuelPrice illustration.
Key takeaways
- The Economic Times reports that insurers, financiers, used-car platforms, charging companies and fleet operators are potential users of connected-vehicle data.
- Published Hyundai and Mahindra documents show that connected services or telematics can involve trip, location, diagnostic, driving and charging information.
- IRDAI material has discussed pay-as-you-drive, pay-how-you-drive and telematics products, but this report does not announce a blanket change to motor-insurance premiums.
- Owners can check the data collected, its purpose, sharing partners, retention period, opt-out route and what happens when a connected-service subscription ends.
What the new report says
The report describes a shift in how vehicles are valued after they leave the showroom. A connected car can continuously produce information about where it travels, how it is driven, when it needs service and, in an electric vehicle, how it is charged and used. That information may help a fleet operator manage utilisation and maintenance, while insurers and financiers could eventually use selected records for risk assessment, claims handling or residual-value analysis.
Those are potential uses, not a confirmed new pricing system for every Indian motorist. The report also notes that customer consent, data ownership, cybersecurity and the absence of a common data format remain open issues. As of 04 Oct 2026, readers should treat the development as an emerging industry direction rather than a new nationwide insurance rule.
What connected services can record
Hyundai Motor India’s published Bluelink privacy policy says its application may collect trip count and distance, current and historical vehicle location, diagnostic information, speed, mileage, braking and acceleration data. It also addresses voice and text queries when voice-recognition features are used. The policy says information may be shared with service providers, financiers and insurance providers for stated purposes, and describes an option relating to sending diagnostic, location and trip-log information.
Mahindra’s BE 6 owner’s manual gives a separate example. It says the vehicle’s electronic modules can record information linked to braking, acceleration, trips, charging events, diagnostics, speed, direction and location. It describes wireless transmission for telematics services, troubleshooting, vehicle-quality analysis, research, charging reminders and software updates, while also setting out exceptions and consent-related disclosures.
These documents are not proof that every automaker collects the same fields or that every insurer receives them. They show why the privacy notice for the particular car, app or device matters more than a generic promise that a vehicle is “connected”.
What it could mean for motor insurance
Driving behaviour, distance, time of travel, location, braking and crash information can potentially help an insurer assess risk or investigate a claim. In India, IRDAI’s motor-insurance working-group material has recommended considering pay-as-you-drive and pay-how-you-drive covers and adopting telematics. IRDAI’s policyholder guidance also explains that own-damage premiums vary by insurer, vehicle and coverage. Neither point means that activating connected services automatically earns a discount or raises a premium.
When comparing motor-insurance terms, the useful questions are specific: is telematics optional; which data points influence the price or a claim; how is a driving score calculated; can the owner access or correct the data; how long is it kept; and can the service be stopped without losing unrelated vehicle functions? The difference between a product that offers a usage-linked feature and a policy that makes telematics compulsory should be clear in the policy wording. Readers can also review the difference between third-party and own-damage cover before comparing any add-on or usage-linked feature.
Why fleets and EV owners need a closer look
For a transport operator, trip and vehicle-health data can be useful for planning routes, identifying idle time and scheduling maintenance. The operational benefit depends on data quality, driver consent and how a company uses the records; it is not a guaranteed reduction in fuel or repair costs. Operators can estimate a journey’s fuel requirement separately with the fuel-cost calculator rather than treating a connected dashboard as a substitute for actual operating figures.
EV owners have another layer to consider. Charging history, battery status and fault information can become part of service records or a vehicle-history report. That may help a later buyer understand battery condition, but it also makes it important to ask whether past journeys or charging data remain linked to the vehicle after resale. FuelPrice’s earlier guide on EV battery, charger and roadside insurance checks covers the separate question of what the policy itself includes.
What drivers can check now
- Read the vehicle app’s privacy notice, not only the feature list. Note whether it mentions historical location, driving behaviour, voice data, diagnostics or charging records.
- Separate necessary service data from optional uses such as marketing, research, tailored insurance or partner services. The purpose and the recipient should be identifiable.
- Look for access, correction, deletion and consent-withdrawal instructions. The Digital Personal Data Protection Act, 2023 describes consent as free, specific, informed, unconditional and unambiguous, and provides for withdrawal where consent is the basis of processing; the exact application depends on the relevant law, rules and service terms.
- Before selling or leasing the vehicle, ask how the account is closed, what data is removed, what is retained and whether the next user can see the earlier owner’s history.
- For insurance, read the policy wording for any usage-linked condition, score, device requirement or claim-related data request. Do not assume that a connected feature changes the premium unless the insurer’s dated product terms say so.
What changes now, and what to watch next
Nothing in the 04 Oct report confirms a new nationwide motor-insurance premium, mandatory telematics device or automatic data-sharing rule for private drivers. The immediate change is informational: connected-car data is becoming part of the conversation between automakers, insurers, lenders, fleet operators and vehicle owners.
The next meaningful developments would be clearer consent screens, common telematics formats, more insurer-OEM partnerships, transparent usage-linked policy terms and further regulatory guidance. Until those arrive, the practical reader takeaway is simple: treat connected features as data services as well as convenience features, and check the terms before turning them on.
Sources
- The Economic Times — “Your car knows where you go. Insurers, lenders and automakers want to know too” (04 Oct 2026)
- Hyundai Motor India — “Bluelink Privacy Policy” (2019; accessed 04 Oct 2026)
- Mahindra Electric — “BE 6 Owner’s Manual: Vehicle Telematics and Data Sharing” (2026; accessed 04 Oct 2026)
- IRDAI — “Recommendations of the Working Group on Product Structure for Motor Own Damage Cover” (2019; accessed 04 Oct 2026)
- IRDAI — “Motor Insurance: Policy Holder” (accessed 04 Oct 2026)
- India Code — “The Digital Personal Data Protection Act, 2023” (11 Aug 2023; accessed 04 Oct 2026)
This article is for general information only and is not financial, insurance or legal advice.