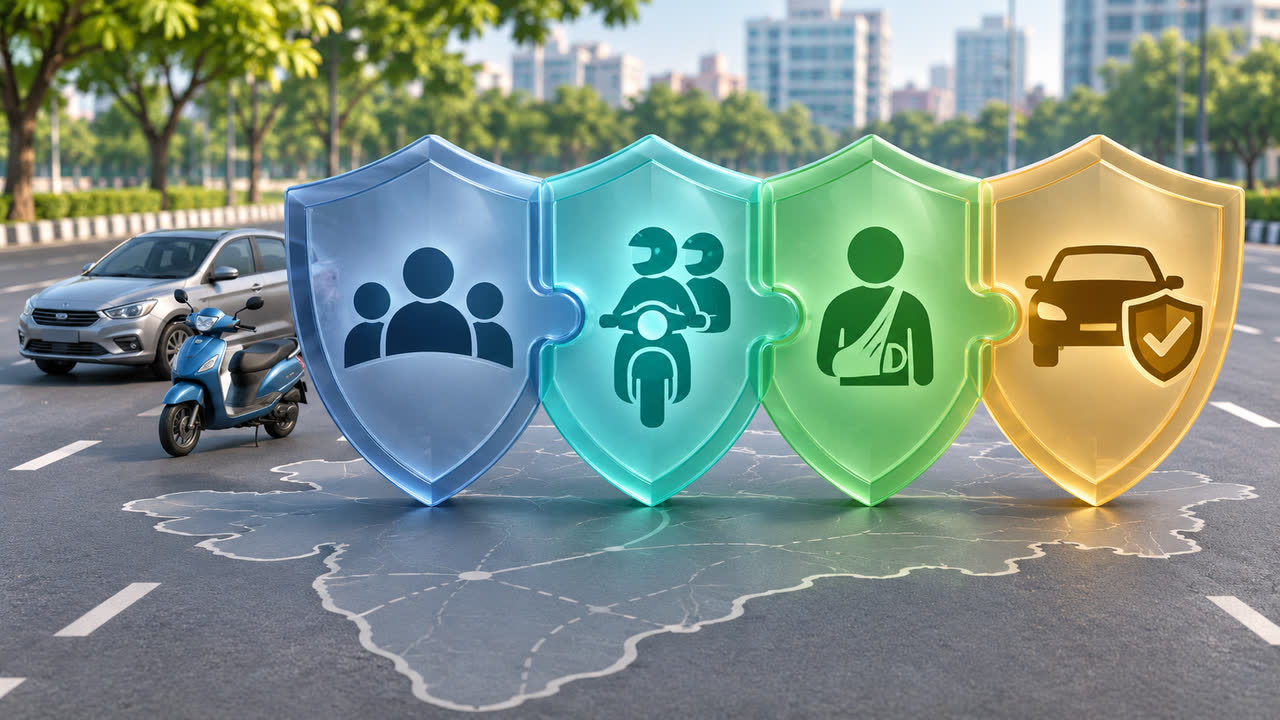
From 15 Dec 2026, IRDAI's new four-layer motor-insurance structure will apply to policies issued for private cars and two-wheelers. It will separate third-party liability, occupant or pillion liability, personal-accident protection and own-damage cover, so the policy schedule shows what is compulsory, what is optional and the premium for each section.
Key takeaways
- Third-party liability and personal-accident cover for the owner-insured remain mandatory under the new structure.
- Occupant or pillion liability and own-damage cover are optional sections, with separate pricing.
- Insurers must provide a customer option form and a Customer Information Sheet at the point of sale.
- An existing third-party policy does not need to be cancelled to add Section II occupant cover, but the addition must be made with the same insurer and takes effect from the endorsement date and time.
Why the motor-insurance format is changing
IRDAI's circular, reference IRDAI/CIR/MOT/10/2026 dated 2 Nov 2026, operationalises the Supreme Court's direction for a clearer four-layer structure for private vehicles. The regulator says the purpose is to make the available protection easier to understand and to let vehicle owners see the cover and premium attached to each choice.
The change is important because a policy that looks like one bundled purchase can contain several different protections. From the effective date, the option form will record the sections selected by the customer, while the Customer Information Sheet will explain the cover available at the point of sale. These documents apply whether the policy is purchased online or offline.
For owners comparing the sections in more detail, FuelPrice's guide to third-party, own-damage and personal-accident insurance explains how the protections differ.
The four sections explained
| Section | Status | What it covers |
|---|---|---|
| Section I: third-party liability | Mandatory | Legal liability for injury, death or property damage caused to another person in an accident. |
| Section II: occupants or pillion riders | Optional | Legal liability towards occupants in a car or a pillion rider on a two-wheeler, including covered employees of the insured. |
| Section III: personal accident | Owner-insured cover mandatory; other occupant cover optional | Personal-accident protection for the owner-insured, with optional protection for occupants, pillion riders and drivers other than the owner-driver. |
| Section IV: own damage | Optional | Loss of or damage to the insured vehicle. |
The split does not mean that every part becomes optional. Third-party liability remains the compulsory legal protection. IRDAI's wording also makes the owner-insured personal-accident section mandatory, while the additional personal-accident protection for passengers, pillion riders and other drivers is optional.
What changes at purchase or renewal
A policy issued from 15 Dec must show the selected protection in the new format. The completed option form becomes part of the policy, and the schedule must reflect the actual cover and premium charged for each section. Insurers have also been directed to use standard wording and complete integration with Bima Sugam from the same date.
The Federal's 22 Nov report, which included an explanation from Insurance Samadhan's Shilpa Arora, said the change should make pricing easier to compare but does not automatically make full protection cheaper. IRDAI has kept insurers free to determine the pricing of own-damage cover in line with market conditions. Actual premiums will therefore still vary by insurer, vehicle, cover selected and policyholder profile.
For a renewal or new purchase issued after the effective date, the practical check is to read the option form and the Customer Information Sheet together. Confirm that the mandatory sections are shown, that any optional cover being paid for is listed, and that exclusions, deductibles, insured declared value and add-on terms are not being assumed from an older bundled policy. This is a document check, not a promise that one cover combination will suit every vehicle or driver.
Owners who want a simple way to track policy dates can use FuelPrice's car-insurance policy date and renewal checklist. The same document checks are relevant to two-wheeler owners, with pillion-related wording read in the context of the policy issued.
What existing third-party policyholders can do
IRDAI has made a specific mid-term provision for Section II. An existing third-party policyholder may add legal-liability cover for occupants or a pillion rider during the policy term by paying the applicable additional premium. The request must be made to the insurer that issued the third-party policy, and the added risk starts only from the date and time stated in the endorsement.
The circular also says that an existing motor third-party policy does not have to be cancelled for the additional cover to be added. That distinction matters when a vehicle owner is checking a renewal or asking for an extra section during an ongoing policy: the policy document and endorsement, rather than a verbal description of a package, determine the effective protection.
What to watch from 15 December
The immediate test will be whether insurers display the four sections, separate premiums and the option form consistently across websites, dealerships and other sales channels. Vehicle owners may see a different policy layout even when the underlying legal requirement for third-party cover has not changed.
The change also makes it more important to keep the option form, Customer Information Sheet, schedule and endorsement together. If a claim or renewal question later concerns passengers, own-vehicle damage or an add-on, those documents show which protection was selected and when it began.
Reader takeaway
IRDAI's four-layer format is a transparency and documentation change, not an automatic premium-cut announcement. For private cars and two-wheelers, the useful comparison is between the cover required by law, the optional risks the policyholder chooses to insure, and the premium and exclusions recorded in the final policy papers.
Sources
- IRDAI, “Four Layer Structure-Motor Insurance Policy”, 2 Nov 2026
- The Federal, “Planning to buy motor insurance after Dec 15? Expert explains why the right covers matter”, 22 Nov 2026
- Moneycontrol, “IRDAI directs insurers to offer 4-part motor insurance cover from December 15”, 4 Nov 2026
- The Times of India, “How motor insurance rules will change from mid-December”, 17 Nov 2026
This article is for general information only and is not financial, insurance or legal advice.