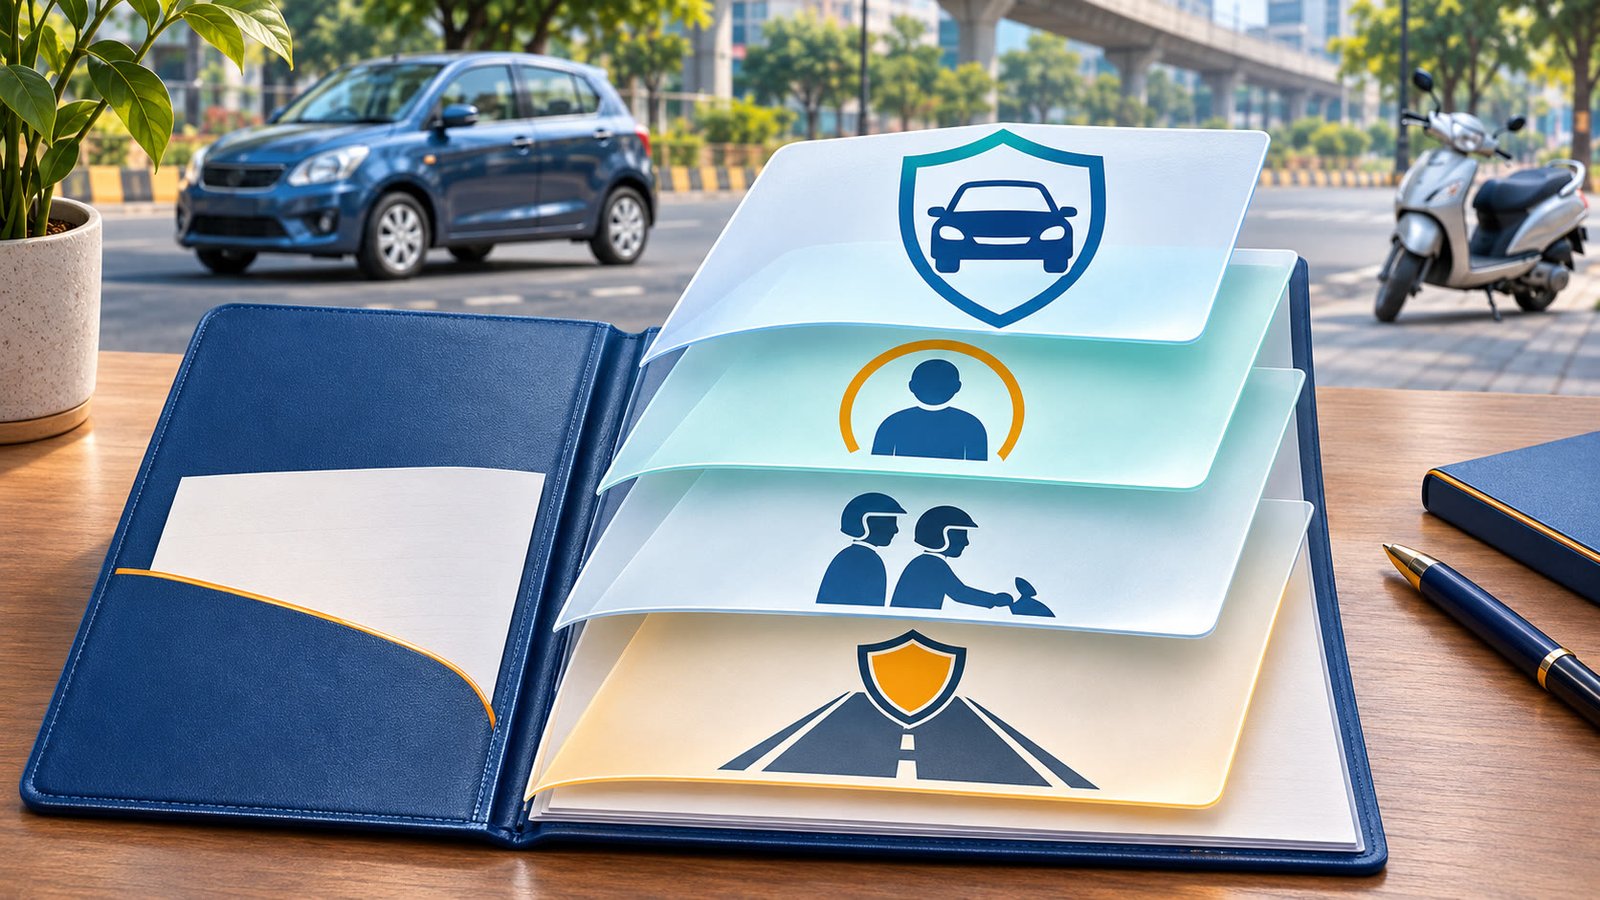
IRDAI has directed general insurers to use a four-layer motor-insurance structure for private cars and two-wheelers from 15 December 2026. For owners, the immediate change is that the policy will show separate cover choices and premiums, with an option form and a Customer Information Sheet before the policy is issued.
The regulator’s circular is dated 2 November 2026. It follows the Supreme Court’s direction to make motor-insurance options easier to understand, but it does not announce one new premium for every car or bike.
Key takeaways
- The new format applies to private-car and two-wheeler policies issued from 15 December 2026.
- Third-party liability remains the mandatory base layer; occupant or pillion, personal-accident and own-damage covers are shown separately.
- Insurers must use uniform policy wordings, collect a customer option form and provide a Customer Information Sheet.
- The policy schedule must show the cover and premium for each section, making gaps easier to identify.
- Actual premiums will still depend on the vehicle, cover selected and insurer’s pricing; the circular does not set one total premium for all owners.
What IRDAI’s circular changes
The instruction is addressed to general insurers selling motor insurance for private cars and two-wheelers. From the effective date, the policy structure is to be presented in four sections with uniform wordings. The option form must be completed online or offline, and the customer must receive an information sheet explaining the available protection.
The four layers, and what each means
- Third-party liability: This is the base policy and the minimum cover required under Section 146 of the Motor Vehicles Act for liability to other people and property.
- Occupant or pillion-rider liability: This is an optional additional cover for eligible occupants or a pillion rider, with the premium determined by the insurer.
- Personal-accident cover: Cover for the owner-insured is mandatory in the structure, while cover for occupants, a pillion rider or a driver other than the owner is optional.
- Own-damage cover: This optional section relates to loss of or damage to the insured vehicle. It is separate from third-party liability, which does not pay for damage to the policyholder’s own car or bike.
The four sections do not mean that every owner is buying four identical products. They are a clearer way to show what is compulsory, what is selected, and what each part costs. The policy schedule should therefore be read section by section rather than only by looking at the final quote.
What owners will see at purchase or renewal
The practical document change is as important as the names of the covers. A buyer should receive the option form and Customer Information Sheet, while the policy schedule should identify the selected cover and premium for each section. That makes it possible to distinguish a third-party-only policy from a policy that also includes occupant, personal-accident or own-damage protection.
The circular’s trigger is the policy issue date. Owners whose new policy or renewal is being issued on or after 15 December should check that the schedule uses the new format and that any optional cover they selected is actually listed. The date on an online payment receipt is not a substitute for checking the issued schedule.
For a plain-language comparison of the main policy types, see this third-party versus comprehensive car-insurance guide. Two-wheeler owners can also use the bike-insurance validity and renewal checklist when checking their policy dates and documents.
Why the change matters for drivers
Motor insurance is often discussed as if “comprehensive” and “third party” were interchangeable. They are not. Third-party cover protects against specified liability to others; own-damage cover deals with damage to the insured vehicle, subject to the policy terms. Occupant or pillion protection and personal-accident protection are separate questions again.
The Supreme Court’s 4 August 2026 judgment said that a standard four-layer structure and a customer-friendly information sheet would help vehicle owners make an informed choice. IRDAI’s circular turns that direction into an operating format for insurers. The benefit for a driver is greater visibility at the point of purchase, not an automatic promise that the total premium will fall.
Checklist before the next policy is issued
- Check the policy issue date and whether the new format applies.
- Read the schedule for third-party, occupant or pillion, personal-accident and own-damage sections separately.
- Match every selected cover to its premium and read the exclusions, deductibles and limits in the policy wording.
- Keep the Customer Information Sheet and option form with the policy documents.
- For renewal, compare the new schedule with the expiring policy so that a cover is not assumed merely because it appeared in an earlier quote.
For a more detailed renewal document checklist, see the car-insurance renewal and cover checklist. The relevant details are the covers actually shown in the issued policy, not a label used in an advertisement.
What to watch next
Insurers now have to prepare their policy wording, quote flow and document delivery for the 15 December start. Watch for the Customer Information Sheet and section-wise premium display when a policy is issued. If an insurer’s quote or schedule does not clearly identify the four sections, the missing detail is a reason to request the policy wording and the completed option form before treating the cover as confirmed.
Sources
- IRDAI — Four Layer Structure-Motor Insurance Policy — 2 November 2026
- Oquilia — IRDAI sets four-layer motor insurance policy for cars and two-wheelers from 15 Dec — 3 November 2026
- Supreme Court Observer — Motor Insurance and Coverage for Vehicle Occupants — 4 August 2026
This article is for general information only and is not financial, insurance or legal advice.